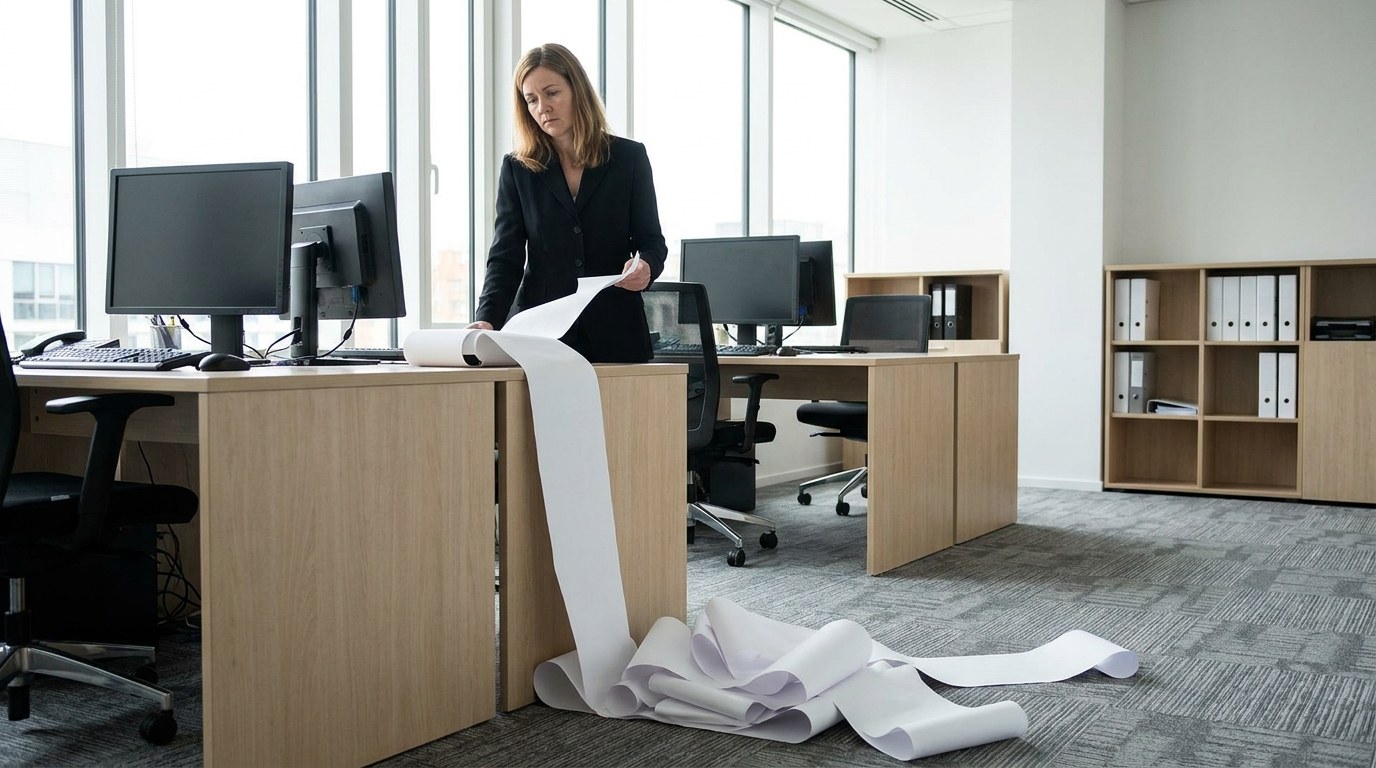
Revenue by customer by month for thirty-six months. Gross margin by product line for the same period. An EBITDA bridge from reported to adjusted, with support for every add-back. Churn by cohort. Pipeline by stage with historical conversion.
That is the second request list from a lead bidder, a composite of the kind that lands a week after first-round bids come in where the sponsor hoped. The confidential information memorandum read well: three years of growth, margins holding, a deep management team.
The CFO reads the list and starts counting. Customer-level revenue lives in two systems that merged eighteen months ago and never fully reconciled. Margin by product exists for this year only, built by hand. The add-backs are in an email thread with the auditors, and churn depends on what you call a customer, which two departments answer differently.
The company is the same company it was last week. What changed is that someone with money on the line is about to find out how well it can describe itself.
Buyers Price What They Can Verify
A sale process runs on confidence, and confidence has a price.
Jay Hernandez, then head of the industrial technology practice at Raymond James, described the mechanism: “The more prepared you are, the more ready you are to answer the questions, answer them cohesively with full punch in there and with full detail behind it to be able to support the statements you’re making, the more confidence you’re putting into the buyer’s mind. And as you do that… that excitement, that competitive nature of a process really starts to ramp up, which then equates to, or translates into, valuation.”
Read it as a chain: preparation produces answers, answers with detail behind them produce confidence, and confidence keeps several bidders leaning in, which is what produces price. It runs in reverse just as well. An answer that takes three weeks, arrives with a caveat, or contradicts the management presentation drains the room, and every bidder who leans back is one less reason for the last one to pay what the CIM implied.
I’ve written about how deferred platform investment gets priced at exit. The package below is what the CFO hands across the table, built so the discount never starts.
”Be the CFO for Your Buyer”
The phrase comes from Rob Turano, an operating partner at Bloom Equity Partners, and he was talking about something else: how Bloom teaches its portfolio companies to sell software. His version:
“Someone told me as a salesperson, you need to be the CFO for your buyer… it’s spot on because one, just what pain point are we solving? And then two, what is the return? So trying to arm your buyer with all of the information that they need to go back to their steering committee, purchasing committee, you name it, to make this as no brainer of an approval process as possible.”
He meant a software buyer justifying a purchase to a finance leader. The same logic holds when the thing being sold is the company.
It holds because the buyer of your company has the same problem at a larger scale: a deal team walking into an investment committee to justify the price. Behind every line on that request list is an IC memo, and every item they cannot source from your data room becomes an assumption they have to defend alone. Assumptions get haircuts.
Being the CFO for your buyer means writing their memo before they do: what pain the business solves, for whom, how durably, and what the return looks like under the growth they are underwriting. Answer those in the shape the deal team needs and the IC conversation is about price. Otherwise it is about risk, and risk is priced by the people most nervous about it.
The same episode sets the clock. By Turano’s count, a fund needs at least four to six quarters of aggressive growth before the market gives credit for it, which, as he put it, puts you in year three of the hold. The data proving those quarters has to exist while they happen.
Why This Is an Analytics Problem
Most exit preparation advice covers timing, the multiple, and which banker to hire, and the request list is where that advice runs out. The banker and the quality of earnings provider build the book from what the company can produce. They cannot invent thirty-six months of customer-level revenue the company never kept.
Every line on the request list is a query, and it only returns a clean answer when the data exists at the grain the question asks for, the definitions behind it have held steady, and someone can explain every place the line moves. That is a data model, a set of definitions, and a narrative layer, and diligence runs all three at full load with a stranger watching.
Most of what goes wrong is a definition problem. Churn by cohort assumes the company has agreed what a cohort is and what separates churn from a downgrade. Margin by product assumes allocations applied the same way for three years. An add-back assumes a boundary between recurring and non-recurring cost that the general ledger was never asked to hold.
A buyer is also paying, in part, for a business that has been institutionalized: one where the knowledge of how revenue is made lives in systems and definitions rather than in the founder’s head. A company whose numbers only reconcile when one specific person is in the room has told the buyer something, whether or not it meant to. That connects to the emotional work founders skip before a sale: owners who cannot describe the business apart from themselves tend to produce records that cannot describe it either.
The Buyer’s CFO Package
So the practical lens is a question: what would the buyer’s CFO ask, and in what form would they need the answer to sign off? Five pieces cover most of the list. Every example below is illustrative.
Revenue broken down the way the buyer will cut it. By customer, by product or service line, by segment, by month, for at least three years, from one source. Steve Hunter, a managing director at TM Capital, described the exercise: “We spend a lot of time with our clients slicing and dicing invoice level data, line item data to try to show that… once a customer buys something, they buy X amount of follow on parts and service, or they buy X amount of replacement parts.” A services company with no contracts can still show durability that way, if the invoice data joins to a stable customer key. If the key is a free-text field, the proof is a project.
An EBITDA bridge with every step supported. Reported to adjusted, each add-back named, sized, and documented at the transaction level, from owner compensation above market to the consultant who built the new ERP. The ones the buyer’s team cannot trace come out of the number they underwrite. An add-back for “non-recurring professional fees” that includes the same tax advisor three years running costs more than its own value, because it makes the reviewer re-check everything else.
KPI trends with a narrative at every inflection. Three years of the operating metrics that drive the model, with a sentence attached to every month where the line bends: gross margin dipped because a supplier repriced and the pass-through lagged sixty days. The buyer will find every bend anyway. With an explanation it is a data point. Without one it is a question for the risk column of the IC memo.
Concentration and churn, defined once. Top-ten customer share by year with contract terms and renewal dates, plus logo churn and revenue churn by cohort, with one written definition applied across the whole period. If the company changed what it calls a customer when it merged systems, say so, show both, and reconcile them. Roll-ups discover this at exit, because every acquisition arrived with its own definition. A company that counts a downgrade as a retained customer will meet a buyer who counts revenue retention instead, and only one of those numbers will be in the model.
Pipeline, if growth is part of the price. Open pipeline by stage, stage definitions, historical conversion by stage, and sales cycle length. Without the conversion history, a pipeline at three times plan is a management estimate.
All of it is the same operating data a well-run company uses on a Tuesday. The difference at exit is the audience: adversarial by design, on a fixed timeline.
Find Your Anomalies Before They Do
The buyer’s associate has a model with a tab for every item on that list and no sense of humor about any of them. Whatever is in your data, they will find.
So the last piece of the package is a sweep. Run the buyer’s cuts on your own numbers a year or more before the process and write down everything that needs a sentence: the month revenue spiked on a prepayment, the customer that is really three affiliated entities, the ERP migration that duplicated six weeks of invoices.
Every one of those has an innocent explanation when the seller offers it first and a worrying one when the buyer discovers it alone. Same fact, different price.
What Faster Diligence Buys
The payoff is mostly in what does not happen. Diligence does not drag on, so deal fatigue never reaches a management team that still has a company to run. Surprises do not surface in week nine, so the price agreed at LOI has a better chance of being the price at close. And the IC memo across the table gets written from your package, in your framing, with your definitions.
If you are the CFO reading this with a sale eighteen months out, the list is long and you have a day job. The package does not get built in the weeks before launch, and most of it should never be a project at all. A diligence-ready company was already running on those numbers during the hold. The exit is simply the first time someone outside the building checks.
So here is a test for this week. Pick the line at the top of this post you would least like to see on a real request, and time how long it takes to produce from your systems today. Hours means the package is mostly built. Weeks means you have found where it starts, before the buyer’s associate did.
Sources: BluWave podcast (Jay Hernandez, 2023; Steve Hunter, 2025; Rob Turano, Bloom Equity Partners).
Alex Escoriaza helps PE-backed companies build the data model, the definitions, and the KPI narrative that hold up when a buyer’s team starts asking questions. If one line on that list would take weeks, that is the line to start with, during the hold and long before a banker is involved. It is the kind of work I do. Start with that line.